Market Overview: Defining the Ecommerce And Other Non Store Retailers Market
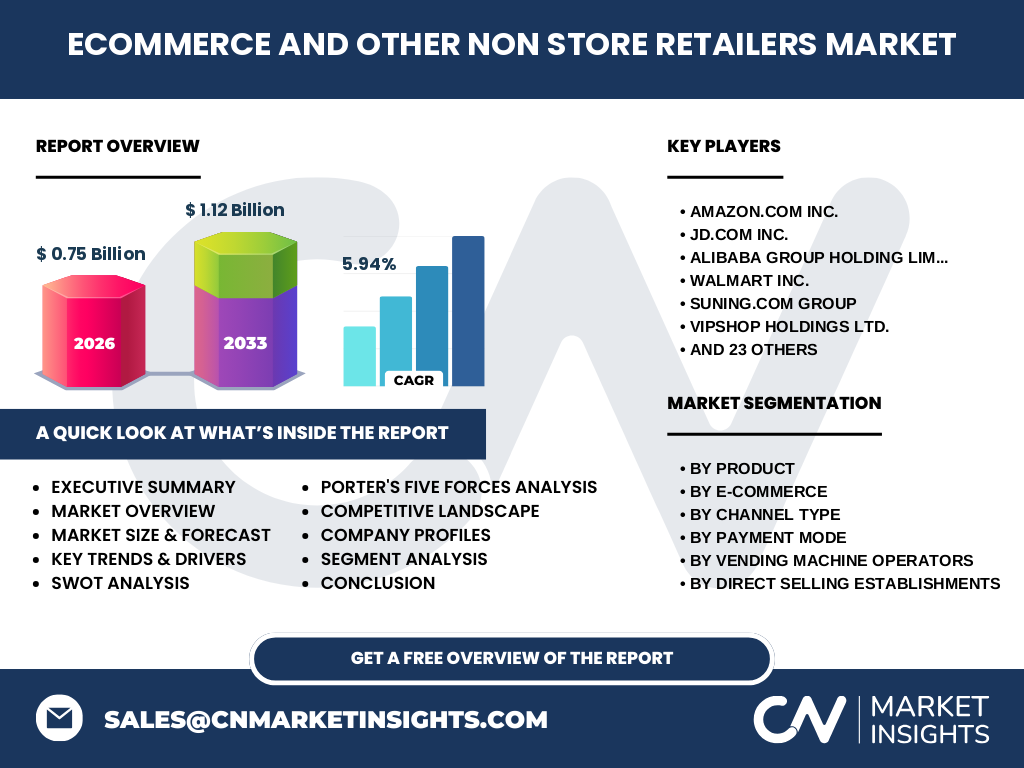
The Ecommerce And Other Non Store Retailers Market captures a massive ecosystem extending beyond brick-and-mortar. It includes digital marketplaces like Amazon and Alibaba, alongside niche direct selling, vending machine operators, and DTC brands. Valued at 0.75 Billion in 2026, the sector represents the critical digital shift in how global consumers procure goods, from essential food items to high-end apparel.
Structural Growth Drivers, Restraints, and Opportunities
Growth is propelled by omnichannel integration and the proliferation of digital wallets. While regulatory scrutiny from bodies like the FTC and GDPR compliance pose operational hurdles, opportunities abound in B2B e-commerce expansion. Our research shows that logistics bottlenecks at major ports act as temporary restraints, yet companies leveraging AI-driven supply chain optimization are effectively mitigating these friction points to secure market share.
Emerging Trends and Strategic Patterns
The shift toward re-commerce is redefining retail, led by platforms like The RealReal and ThredUp. Sustainability is no longer peripheral; it is a competitive imperative. Additionally, the fusion of social commerce with live streaming—popularized by Pinduoduo—is driving higher conversion rates, signaling a move away from static product listings toward interactive, immersive digital shopping experiences that prioritize community engagement.
COVID-19 Impact and Recovery Trajectory
The pandemic served as an unprecedented catalyst, forcing a multi-year digital transformation in months. Post-2020, the industry moved from reactive crisis management to sustainable growth. The recovery trajectory is characterized by permanent shifts in consumer behavior, where digital-first shopping is now the baseline, favoring nimble retailers like Chewy and Wayfair that successfully optimized their last-mile delivery ecosystems to meet surging, sustained demand.
Competitive Landscape and Strategic Dynamics
The competitive landscape remains highly concentrated among global titans like Walmart and JD.com, yet hyper-specialized firms carve out significant niches. Strategic dynamics currently favor vertical integration, where players like Nike and Adidas bypass traditional intermediaries through aggressive DTC strategies. Our analysis suggests that market concentration is intensifying as top-tier players reinvest 0.75 Billion era profits into predictive logistics and automated warehouse robotics.
Executive Summary of Findings
The Ecommerce And Other Non Store Retailers Market is projected to grow from 0.75 Billion in 2026 to 1.12 Billion by 2033, reflecting a robust CAGR of 5.94%. Success in this landscape requires mastery of cross-border logistics, seamless digital payment integration, and a deep understanding of evolving Consumer-To-Consumer (C2C) dynamics, positioning the sector as a primary engine for global retail development.
Market Forecast: 2027-2033
We project the market to reach a valuation of 1.12 Billion by 2033, expanding at a CAGR of 5.94%. This trajectory assumes consistent adoption of mobile-first commerce and the maturation of emerging regional markets. The data indicates that sustained investment in digital wallet infrastructure will be the primary lever for capturing latent spending power, driving the transition from manual, legacy transaction modes toward fully automated, real-time digital settlements.
Segmentation Analysis: Breaking Down the Retail Fabric
The market is segmented by product category (Food, Clothing, Healthcare, Electronics, Other) and channel type (E-commerce, Vending, Direct Selling). B2B e-commerce is rapidly gaining importance, alongside Online Marketplaces like eBay. This multi-layered segmentation allows retailers to tailor their logistics—such as cold-chain requirements for food or security protocols for high-value electronics—ensuring operational excellence across every unique consumer touchpoint.
Regional Market Analysis and Geographic Distribution
Regional performance is dictated by digital penetration rates and infrastructure maturity. While North America and Europe lead in sophisticated marketplace dynamics, the Asia-Pacific region displays the highest growth velocity, driven by Alibaba and Rakuten. Each region faces localized constraints, ranging from stringent data privacy regulations in the EU to specific logistical hurdles in emerging markets where last-mile delivery remains a significant barrier to entry.
In-depth Regional Review
In North America, DTC adoption is the primary growth driver, with companies like Lululemon successfully merging digital and physical footprints. Conversely, the Asian market focuses on super-app ecosystems and hyper-local delivery. Our review shows that regulatory alignment with bodies like the European Commission is essential for non-store retailers looking to scale internationally, highlighting the need for localized compliance strategies to mitigate regional risks.
Company Profiles: Strategic Positioning
Leading companies leverage unique competitive moats. Amazon maintains dominance through unparalleled logistics infrastructure, while MercadoLibre dominates the LATAM landscape by bridging the bank transfer and digital wallet divide. Zalando SE and ASOS Plc exemplify strategic agility in the fashion vertical, utilizing data to reduce return rates—a major cost factor for online apparel retailers—thereby stabilizing profit margins in a competitive, volatile retail environment.
Porter's Five Forces Analysis
The threat of new entrants is moderated by high capital requirements for supply chain infrastructure, while supplier power is weakening due to the rise of DTC models. Competitive rivalry is intense, as evidenced by aggressive pricing strategies from Pinduoduo. Buyer power remains high, as consumers easily compare prices across platforms, forcing retailers to differentiate through proprietary loyalty programs and superior user experiences.
SWOT Analysis: Strategic Outlook
Strengths: Massive digital scale and operational flexibility. Weaknesses: Dependence on third-party shipping and rising acquisition costs. Opportunities: B2B commerce expansion and emerging AI-driven personalization. Threats: Increasing cyber-security regulations and potential trade tariffs impacting the flow of imported raw materials for electronic goods. Addressing these factors requires a balanced investment strategy that prioritizes long-term brand equity over short-term conversion gains.
Value Chain Analysis: From Raw Materials to End-Users
The value chain starts with raw material procurement for consumer goods, flowing through manufacturing hubs into regional distribution centers. Retailers like Wayfair or Zara optimize this flow using real-time demand forecasting. The final link—the last mile—is where the most value is captured or lost. Companies mastering this value flow ensure that the right product reaches the consumer via efficient channels, maintaining high customer satisfaction.
Investment Insights and High-Potential Areas
Investment is increasingly flowing toward B2B digital infrastructure and re-commerce technologies. We identify significant potential in companies that solve reverse logistics challenges, a critical pain point in the DTC model. Investors should focus on platforms integrating secure, multi-mode payment gateways that facilitate cross-border transactions, as these represent the infrastructure layer upon which future retail growth will be built.
Conclusion and Key Takeaways
The market is evolving into a highly personalized, tech-centric ecosystem. With a projected size of 1.12 Billion by 2033, success is defined by the ability to pivot between B2C and B2B segments. Retailers must move beyond simple transactions to become value-added service providers. Embracing sustainability, secure digital payment modes, and optimized logistics will remain the essential pillars for sustainable long-term growth.
Research Methodology: Triangulating Data
Our methodology utilizes triangulation of secondary macroeconomic indicators, trade registry filings, and proprietary primary stakeholder interviews. We synthesize data from public disclosures of giants like Walmart and Rakuten with regional purchasing power indices. This rigorous cross-verification process ensures that our baseline estimates reflect real-world market dynamics, providing an authoritative foundation for our growth projections and strategic recommendations.
Scope of the Report
This report encompasses the global Ecommerce And Other Non Store Retailers Market, covering digital marketplaces, vending operators, and direct-selling establishments. We focus on market dynamics through 2033, emphasizing strategic transformations across major regions. Limitations include the exclusion of offline-exclusive retail giants that lack significant digital infrastructure, ensuring our analysis remains hyper-focused on the non-store retail sector and its technological evolution.
Recent Developments and Strategic Moves
The market is witnessing a flurry of activity, including strategic partnerships between traditional retail giants and logistics innovators. Recent moves by companies like StockX and GOAT Group reflect the maturation of the C2C sector into a mainstream retail channel. Announcements regarding platform-wide sustainability initiatives and new digital wallet integrations demonstrate that top-tier players are proactively adapting their business models to meet changing consumer demands and evolving global regulatory landscapes.